
Singapore's Big Three Banks See Firm Q2 2026 Earnings on High Rates, Wealth Growth
Singapore's three largest banks are projected to report firm earnings for the second quarter of 2026, primarily supported by elevated interest rates and an expansion in wealth management activities. Investors are closely assessing the durability of these revenue drivers into the latter half of the current year.
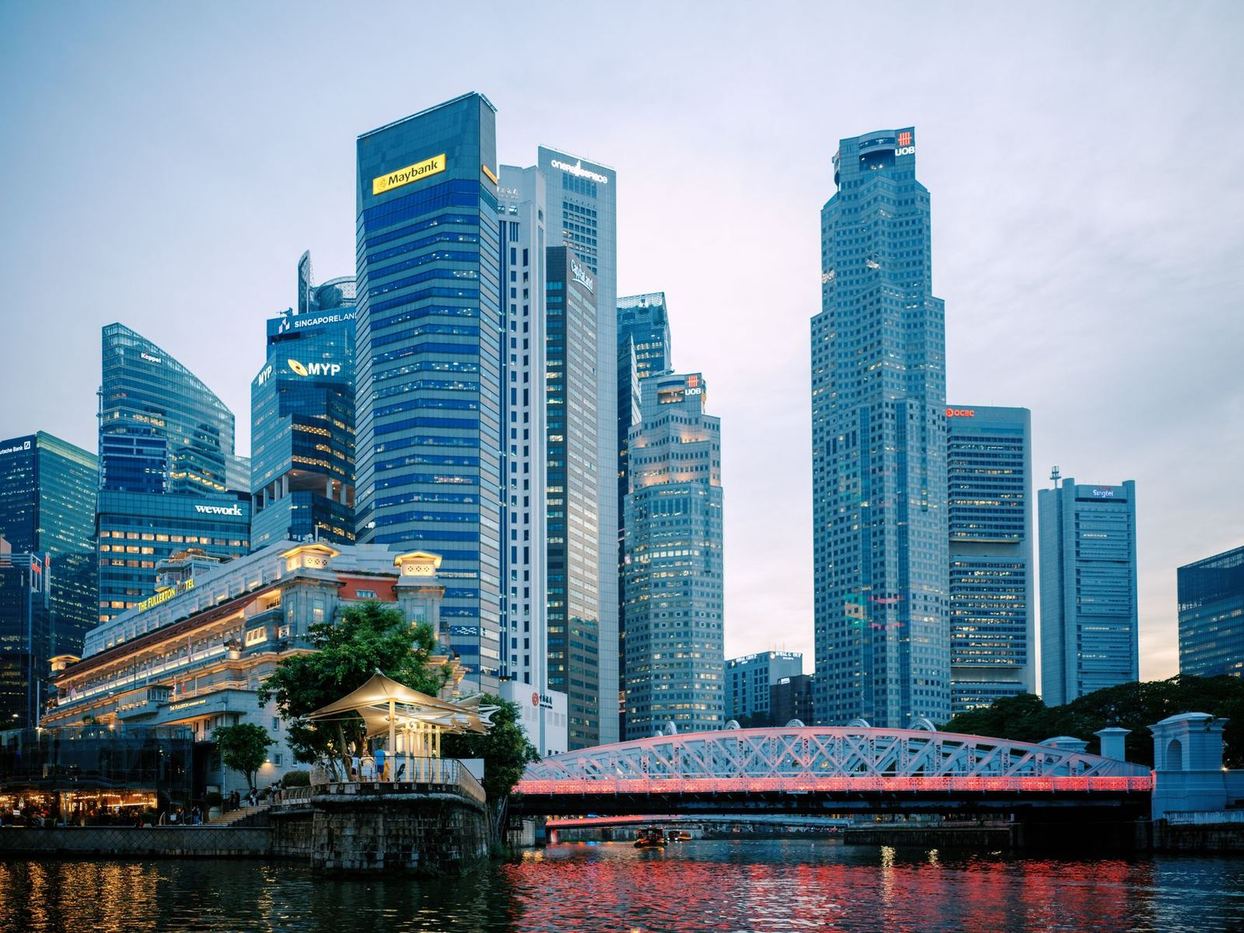
Expected Q2 Performance and Key Drivers
Singapore's major financial institutions, including DBS Group, Oversea-Chinese Banking Corporation (OCBC), and United Overseas Bank (UOB), are anticipated to demonstrate firm earnings results for the second quarter of 2026.
This performance is primarily attributed to sustained higher interest rates, which have broadened net interest income, alongside an increase in loan volumes across their portfolios. Concurrently, these banks have benefited from a notable expansion in their wealth management services, contributing significantly to non-interest revenue streams.
DBS Group is scheduled to release its Q2 2026 financial outcomes on 6 August, with OCBC and UOB following on 7 August. These reports will offer the first detailed view of the sector's financial health for the quarter ending June 2026, as observed by analysts. The convergence of these factors suggests a period of stable revenue generation for the sector.
Investor Focus on Sustainability and Margins
Beyond the immediate Q2 2026 figures, investors are directing their attention towards the sustainability of these key earnings drivers into the second half of the current year. A primary area of scrutiny involves net interest margins (NIMs), with analysts monitoring whether the downward pressure observed in previous periods has entirely dissipated.
While elevated interest rates have generally supported NIMs, the market is keen to understand if the peak benefit from rate increases has been realised or if further margin expansion is plausible. The trajectory of loan growth and the continued momentum in wealth management income will also be critical indicators.
Analysts are examining whether the current pace of expansion in these segments can be maintained, particularly as global economic conditions evolve. The forthcoming earnings calls will provide management commentary on these forward-looking aspects, which are crucial for assessing the banks' medium-term outlook.
The Nuance of Interest Rate Dynamics
While higher interest rates have been a significant positive factor for Singaporean banks' earnings, the market remains attentive to the dynamics of these rates. The current interest rate environment, which has contributed to firm net interest income, is subject to shifts in global monetary policy and domestic economic conditions.
A potential counter-argument to sustained earnings momentum centres on the possibility of a plateau or eventual moderation in interest rates, which could temper future net interest income growth. Furthermore, competitive pressures within the lending market could also influence NIMs, even in a generally higher rate environment.
Analysts will be evaluating management's guidance on their expectations for interest rate movements and how the banks plan to manage their balance sheets to mitigate any potential compression in margins. The ability to diversify revenue streams, particularly through non-interest income from wealth management, becomes increasingly important under such conditions.
Implications for Regional Financial Sector Performance
The Q2 2026 results from Singapore's leading banks carry broader implications for the financial sector across Southeast Asia, given their significant regional presence and cross-border operations. A consistent performance, driven by interest rates and wealth management, would demonstrate the continued resilience of regional financial markets against global economic shifts.
Conversely, any unexpected contraction in net interest margins or a deceleration in wealth management income could suggest a broader trend affecting other regional banks that operate under similar economic conditions.
Decision-makers should specifically observe the banks' guidance on loan loss provisions and asset quality, which will offer insights into the health of the broader credit environment. The detailed Q2 reports, available after 7 August, will provide critical data points for evaluating the financial sector's near-term trajectory and capital allocation strategies in Asia.
This analysis is journalism, not investment advice; consult a licensed professional before making financial decisions.
Pieces are credited to the desk that commissioned and edited them. Our editorial standards, and the desks behind them, are set out on the Editorial Standards and Team pages.
Further reading
- Briefings · Markets
SoftBank Group shares drop 11% after OpenAI delays IPO
The Tokyo-listed investment firm saw its stock decline significantly earlier this week, following an announcement from OpenAI that it would delay its initial public offering and advocate for slower AI development.
Continue reading → - Briefings · Policy
Will South Korea's Corporate Tax Rate Be Reduced?
Finance Minister nominee Lee Hyoung-il confirmed on Sunday that the 25% corporate tax rate, reinstated this year, will not be lowered, influencing business investment forecasts for the coming fiscal periods.
Continue reading → - Briefings · Policy
RBI proposes freezing accounts for cyber fraud
India's central bank seeks public input on proposed amendments to its Know Your Customer directions, aiming to formalise how banks can temporarily freeze accounts linked to cyber fraud by October 2, 2026.
Continue reading →